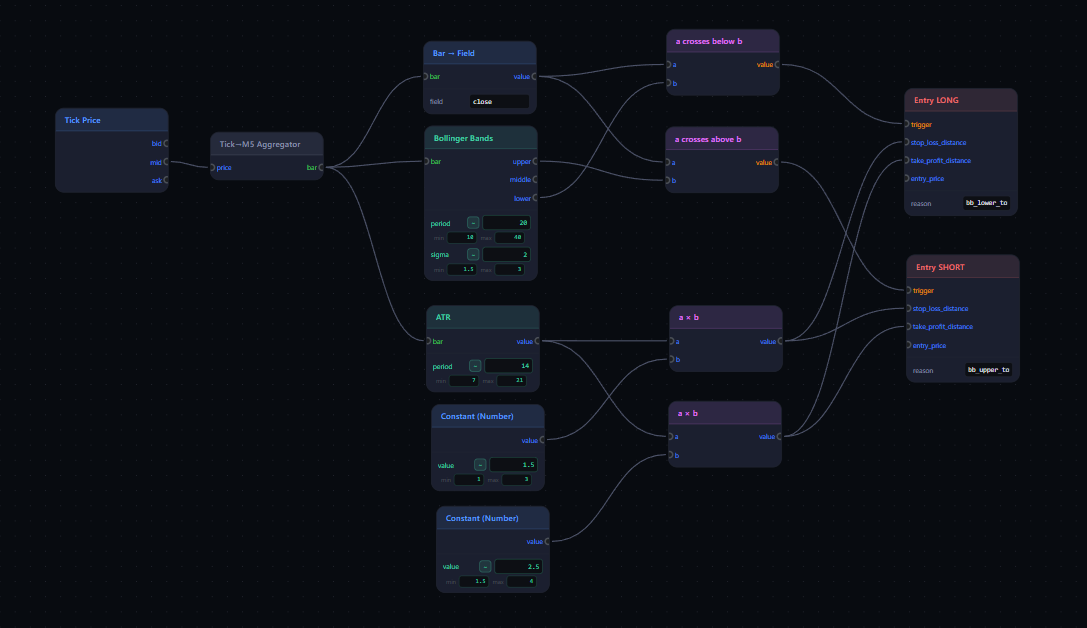
The graph editor: 98 block types, their inputs and outputs typed and connected visually. No code required.
Build trading strategies visually, describe them in plain text, or import Pine Script. Test against your own historical trading data. See the numbers before you risk anything.
The graph editor: 98 block types, their inputs and outputs typed and connected visually. No code required.
Most tools simulate on bar data with generic feeds. Real execution happens on ticks, with your broker's actual spreads. The difference shows up in your live results.
Every piece of the strategy development process in one place.
98 block types in 9 categories. Connect indicators, conditions, and signals as strictly typed blocks. Invalid connections are rejected before you run, not after.
Particle swarm optimization searches the parameter space for the combinations with the highest value of the fitness function you choose: profit factor, Sharpe, Sortino, Gain to Pain, Calmar or net profit.
Split data into in-sample and out-of-sample blocks. WFO (Premium) runs PSO independently per block, so parameters are never tuned on data they're tested against.
Already have a TradingView strategy? Import it: an external AI model converts the script into a graph of blocks. Check the graph, since not every part of a script is converted. Then run it against your own tick data to see how results compare.
Describe your strategy in plain language. partiqon's AI builds a valid graph from it, using only blocks of the catalogue. You see every node and can adjust before testing.
Walk each tunable parameter across a grid around its current value and see how much the result depends on it, at the neighboring settings as well as at the chosen one.
Backtest with spreads widened on every fill, on a random share of them or inside a date window, and against a simulated broker account whose margin calls close positions. Margin is checked along each bar's price path, not only at its close. See how the result changes when trading gets more expensive.
Catches patterns that inflate results without you noticing, such as a high profit factor that comes from a single outlier trade. A second pair of eyes on your backtest, built into the platform.
Visualizes the fitness landscape around your PSO optimum. A broad plateau means neighbouring parameter values measured about the same as the optimum; a narrow spike means they measured far lower.
Measures an exit rule against randomized entries, or an entry signal against a fixed exit, over many random seeds on your data. It shows where the rule's figures lie among the figures that chance alone produces on the same bars, before a strategy is built around it.
Chain backtests, optimizations, and walk-forward runs into automated sequences. Build multi-step workflows and come back to results instead of a progress bar.
Sharing is voluntary: your strategies stay private unless you submit one. A shared template holds the structure of a strategy: its blocks, how they are connected, its formulas, and your choice in settings that pick from a fixed list. Every other setting is set back to its default, and numbers inside a formula stay only where you choose to keep them; your results, your data and your optimisation ranges are never part of it. We review each template before it is listed, you can withdraw yours at any time, and readers can report one. Any account can open a published template as a new strategy of its own. What we store with it is in the privacy policy.
No configuration overhead, no boilerplate to write.
Connect blocks visually, import an existing Pine Script strategy, or describe what you want: "buy when RSI crosses below 30 and price is above the 200 EMA, exit after 15 bars or when RSI crosses above 70." partiqon converts plain language into a runnable graph. The type system prevents invalid connections before execution.
Convert your own historical price data to BAR6 format using DataConvert (free, runs locally; raw data never leaves your machine). Upload the converted file and select your timeframe.
Set date range and capital. Fills use the bid/ask in your data; for bars without quotes you set a fallback spread. Results include equity curve, full trade list, profit factor, Sharpe ratio, max drawdown, and a per-trade breakdown. If the equity reaches zero, the chart marks the point and the results give its date: the backtest itself runs on below zero, a real account could not.
Mark constants as tunable. PSO searches the parameter space. Walk-forward validation measures the results on data the parameters were not chosen on. WFO runs PSO independently per in-sample block, so each out-of-sample block is measured on data its parameters were not tuned on.
Most tools only tune the numbers in a strategy you already built. Structure Finder builds new strategies on your data and searches over their structure.
Typed mutation (block swaps, parameter jitter, subgraph insert/delete) and crossover generate complete strategy candidates: hundreds with the default settings, thousands in a larger run. The search produces entirely new structures, not only better parameters for a fixed one.
Each candidate's parameters are fitted on the in-sample part of every walk-forward fold, and the candidate is scored on the out-of-sample part that follows. The search selects by that score, so among many candidates the best scores include chance results. The held-back final part of your data, which neither the fitting nor the search reads, is measured once at the end.
Before the search starts, the in-sample data of each walk-forward fold is tested for 36 simple conditions, such as three falling closes in a row or a close above the highest high of the last 20 bars. A condition counts as found only if the bar after it moves differently than after all other bars, with a correction for testing many conditions at once. Findings are shown with their figures and measured out of sample; they do not steer the search. The correction runs within each window. With the default of three folds, on data without structure about one run in ten lists a condition in at least one fold; a run can use 1 to 12 folds, and more folds raise that share. Each condition shows in how many folds it was found. When no condition passes the test, the view says so. Tick data is tested on 1, 5, 15 and 30 minute bars.
Among the generated candidates, many fit chance. After the search, the candidates on the run's shortlist are backtested again on their out-of-sample folds with the entry replaced by unrelated generated entries: the random-entry test Diagnostic Mode applies to exits. The result, whether a candidate's figures depend on its entry timing, is shown with the candidate and can be used as a filter. No candidate is removed, and the check can be switched off for a run.
Structure Finder runs are Premium-exclusive and draw from a dedicated budget, separate from your normal backtest quota.
The data you test on sets how closely a backtest reflects the prices and costs a strategy would have met. partiqon solves this differently.
Most tools backtest on bar data from aggregated feeds, not on what your broker actually quoted. The same instrument can be priced differently from one broker to the next: different spreads, different fills, sometimes a different underlying feed entirely. Test on the wrong data and a strategy can look solid in backtesting, then perform quite differently once you trade it at your actual broker. The gap is systematic, not random.
You bring your own historical data. The backtest runs on what you would actually have traded. Your data stays your data.
A free, open-source tool that converts raw data (CSV, MT4 .hst) into BAR6, partiqon's binary format. It runs locally, so raw data never leaves your PC.
Compact, fast, openly documented. Supports bar data (OHLC + bid/ask) and tick data. No vendor lock-in.
These are not limitations. They are decisions.
partiqon does not generate buy or sell signals. There is no "AI recommends long." The platform evaluates your ideas. It does not replace your judgment.
partiqon does not execute orders and has no connection to your brokerage account. No automated trading through our servers.
partiqon does not buy market data and does not resell it. BYOD is the philosophy, not a workaround.
partiqon does one thing well: making your strategy ideas testable. Portfolio management and news feeds are intentionally not in scope.
Start free. Upgrade when you need optimization and validation.
Annual billing: Pro at €29 / month, Premium at €65 / month. Text2Strategy: 5 requests a month on Free, then a daily limit of 20 on Pro and 50 on Premium.
Features we plan to build. We ship when it's ready, not before.
Execute your tested strategies on live market data. The same logic you tested in the backtest will run in real time, signal by signal.
Programmatic access to all platform features: trigger backtests, read results, manage graphs. For automation, custom dashboards, and integrations.
partiqon launches in invite-only mode. Leave your email and we'll let you know when it's your turn.